If you already own buy-to-let properties and are thinking about moving into larger HMOs, it can be tempting to see it as the natural next step. After all, if you already understand property investment, tenant management, and mortgage finance, how different can it really be?
The honest answer is: very different.
A large HMO is not simply a bigger buy-to-let, and it is not even just a larger version of a smaller HMO. Once you move into this part of the market, you are dealing with a different level of complexity across planning, finance, valuation, compliance, and day-to-day management. The potential returns can be excellent, but the risks are also significantly higher if you approach it with the mindset of a standard landlord rather than an operator.
I say that from personal experience, because one of my own HMO investments taught me exactly how quickly a deal can become more complicated than it first appears.
Generally, when I talk about large HMOs, I mean properties with seven or more rentable bedrooms. In planning terms, these larger properties often fall into Sui Generis use, which immediately creates a different set of considerations compared with smaller residential investments. That matters because lenders, valuers, and local authorities may all assess the property very differently from a standard buy-to-let or even a smaller HMO.
There are broadly two ways investors enter this space. One is buying an already operating HMO — where the property is licensed, income-producing, and theoretically ready to finance on a specialist HMO mortgage. The other is acquiring something that needs conversion, refurbishment, or repositioning, often using bridging finance before refinancing onto a long-term product.
On paper, buying an existing HMO sounds easier. If the property already has tenants, income history, fire safety systems, and the correct permissions, you avoid a lot of upfront work. But inherited problems can be just as dangerous as visible ones — and one of my own purchases was a perfect example of that.
The deal that looked simple on paper
A few years ago, I came across a seven-bedroom HMO near a hospital in a North West town. The owner was retiring, demand in the area looked strong, and from an investment perspective it seemed like an excellent opportunity. I wanted that property immediately. Looking back now, I can admit that I was probably focusing more on the upside than the risks.
The property at acquisition
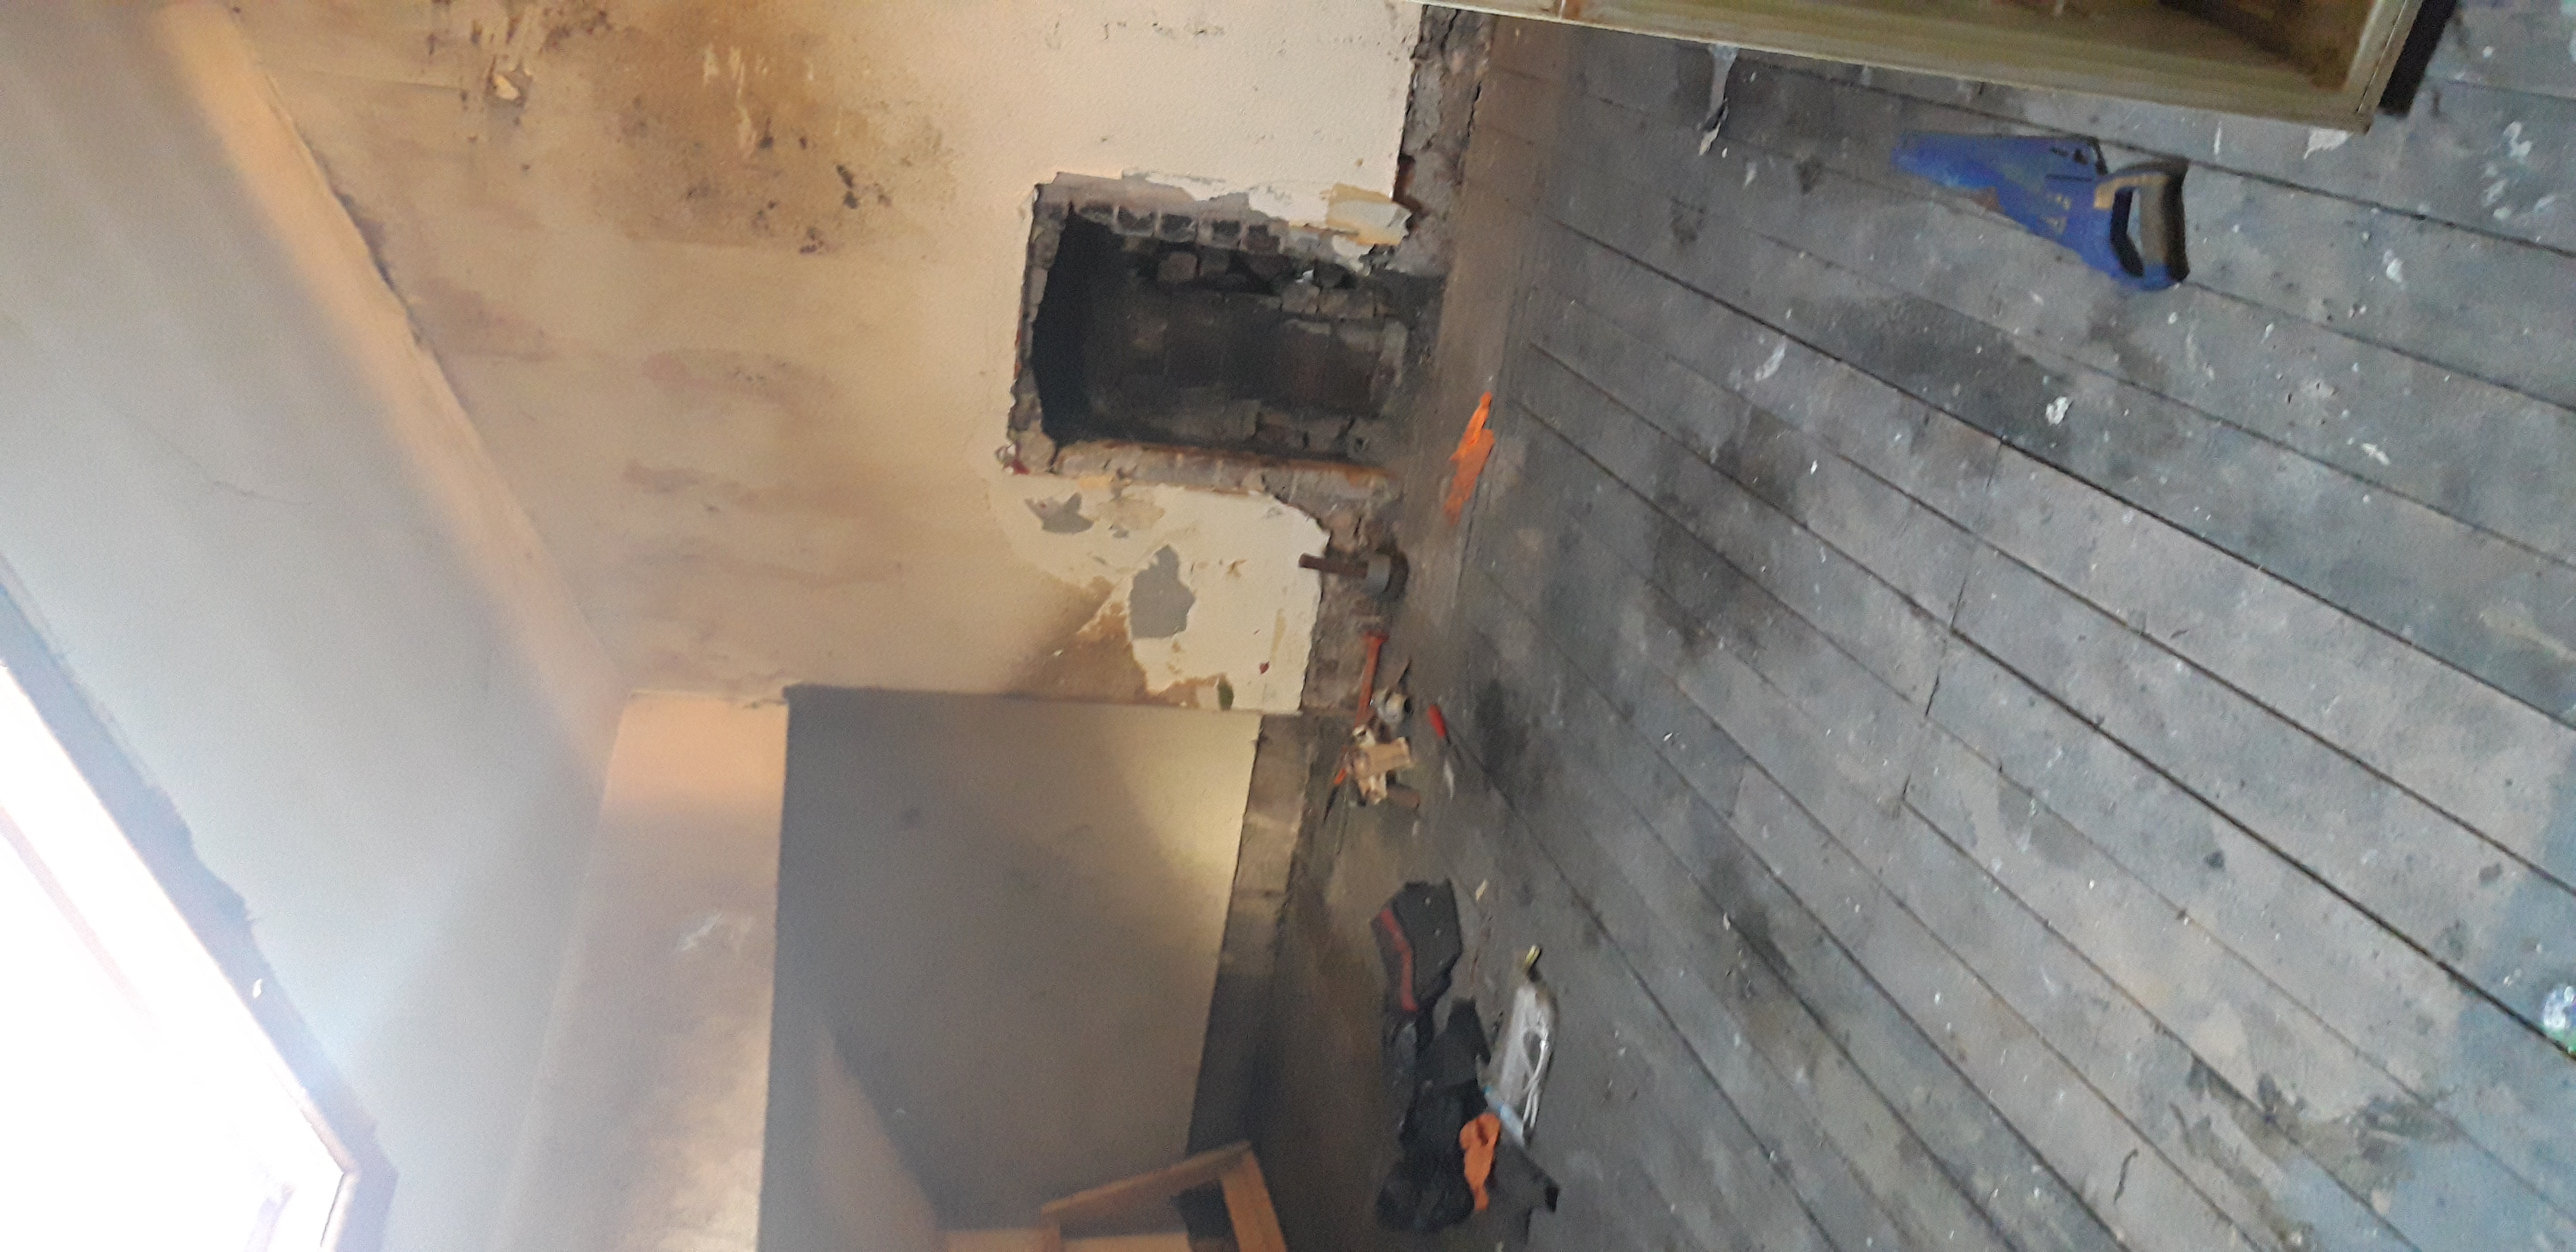
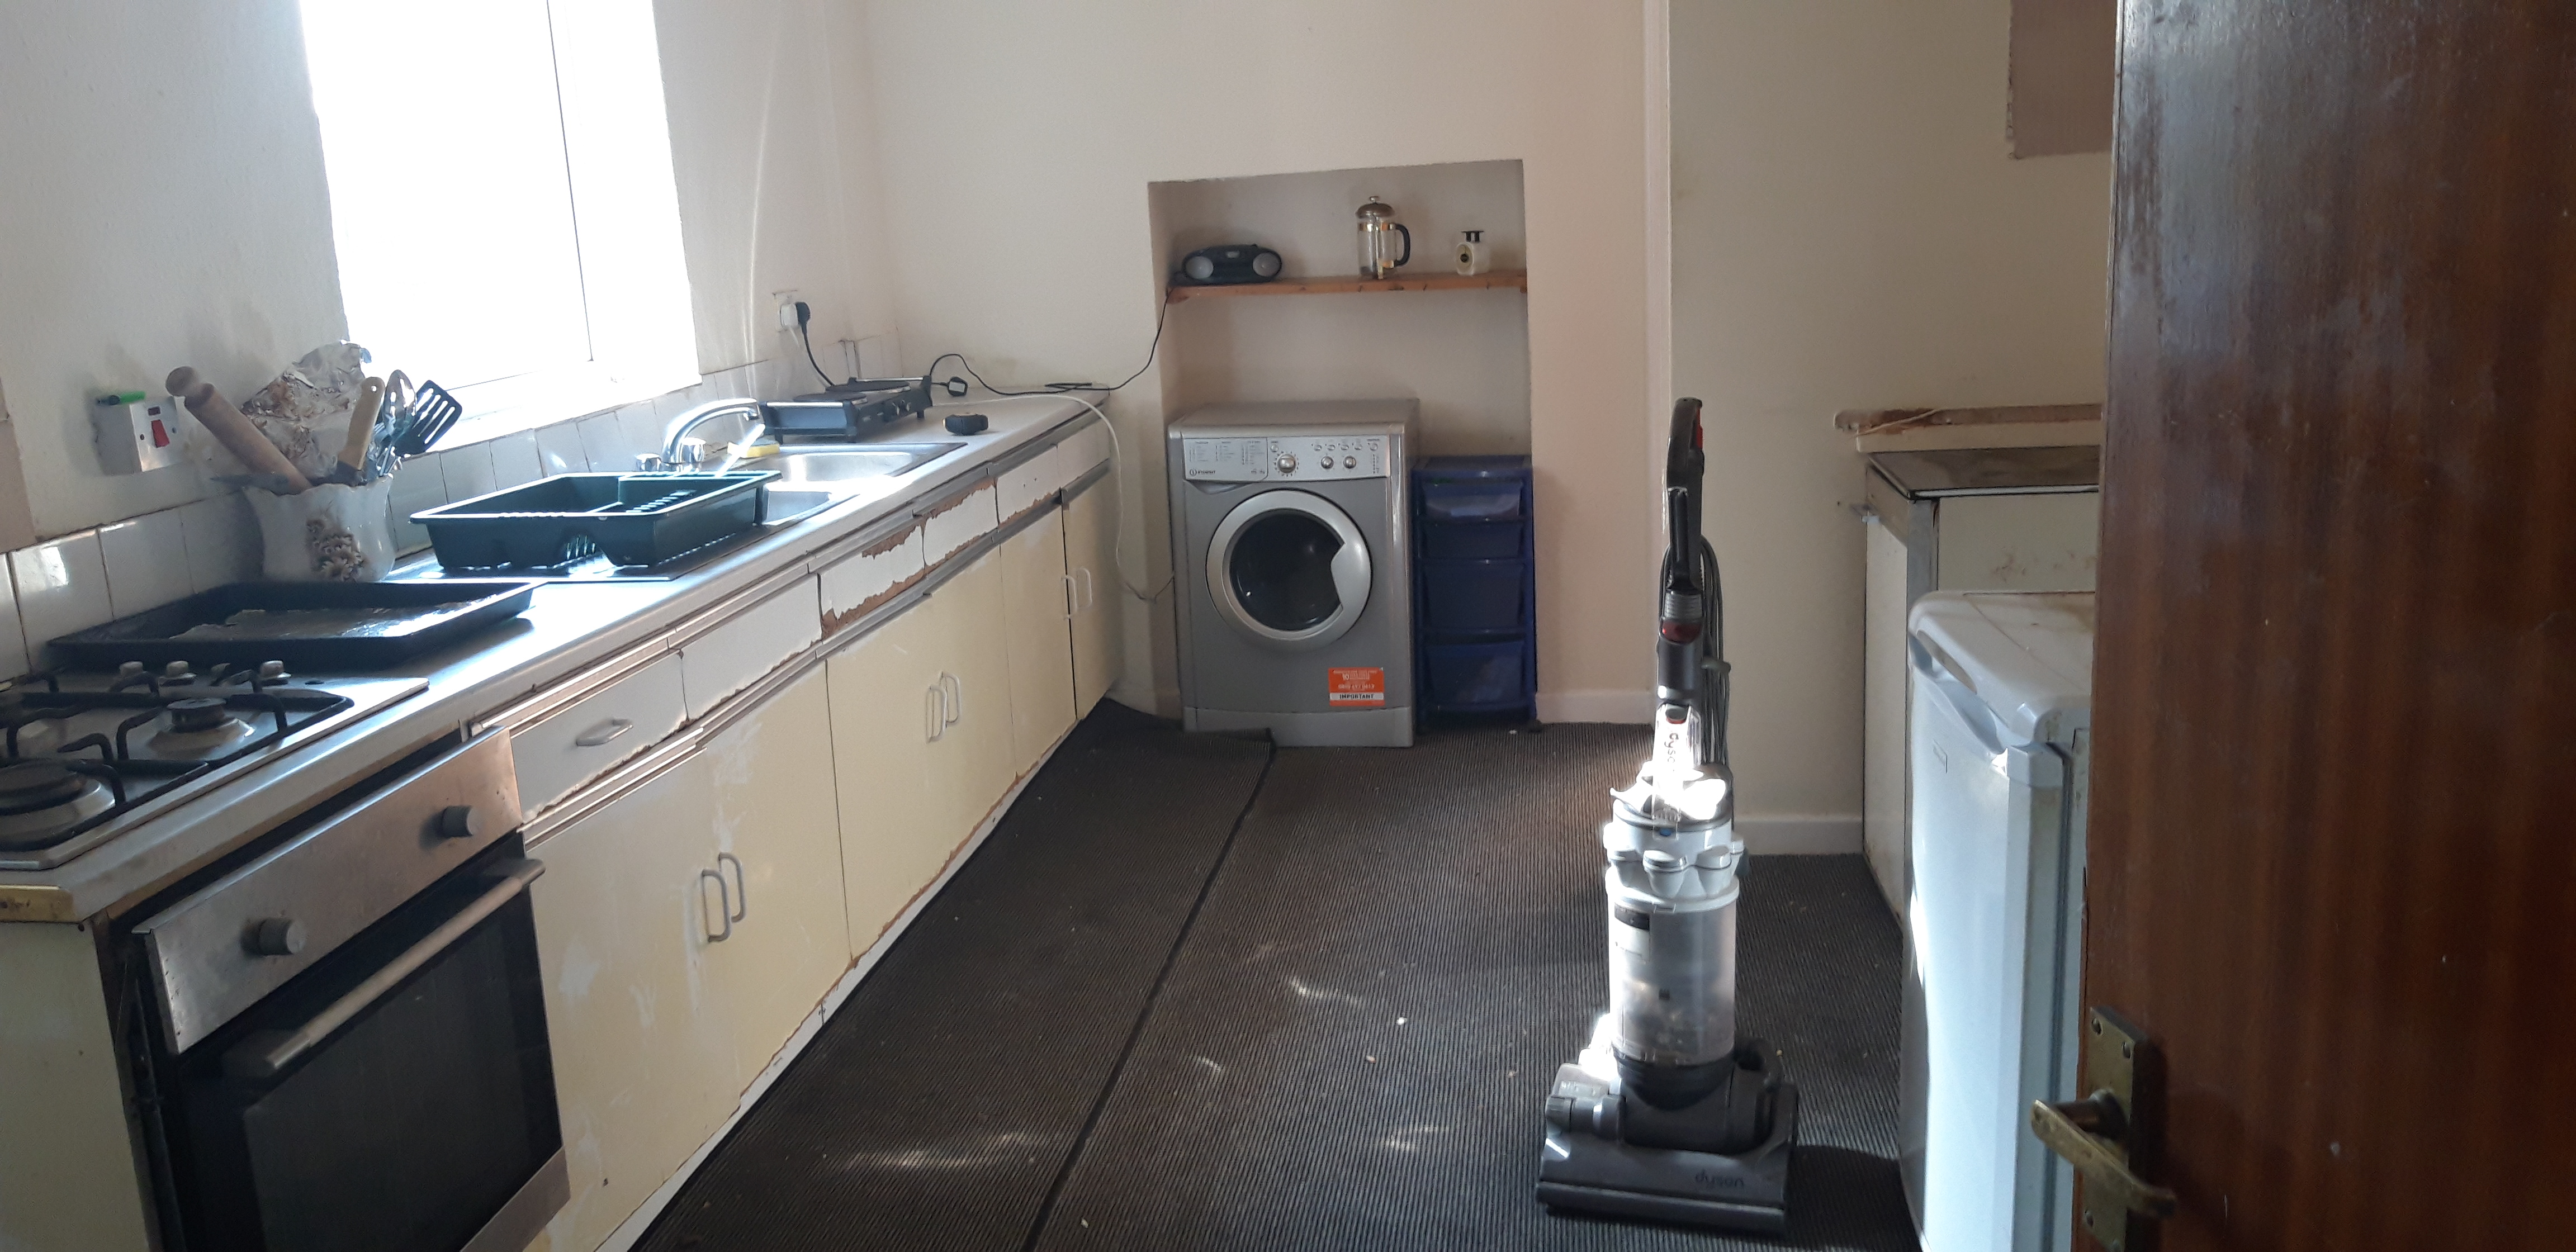
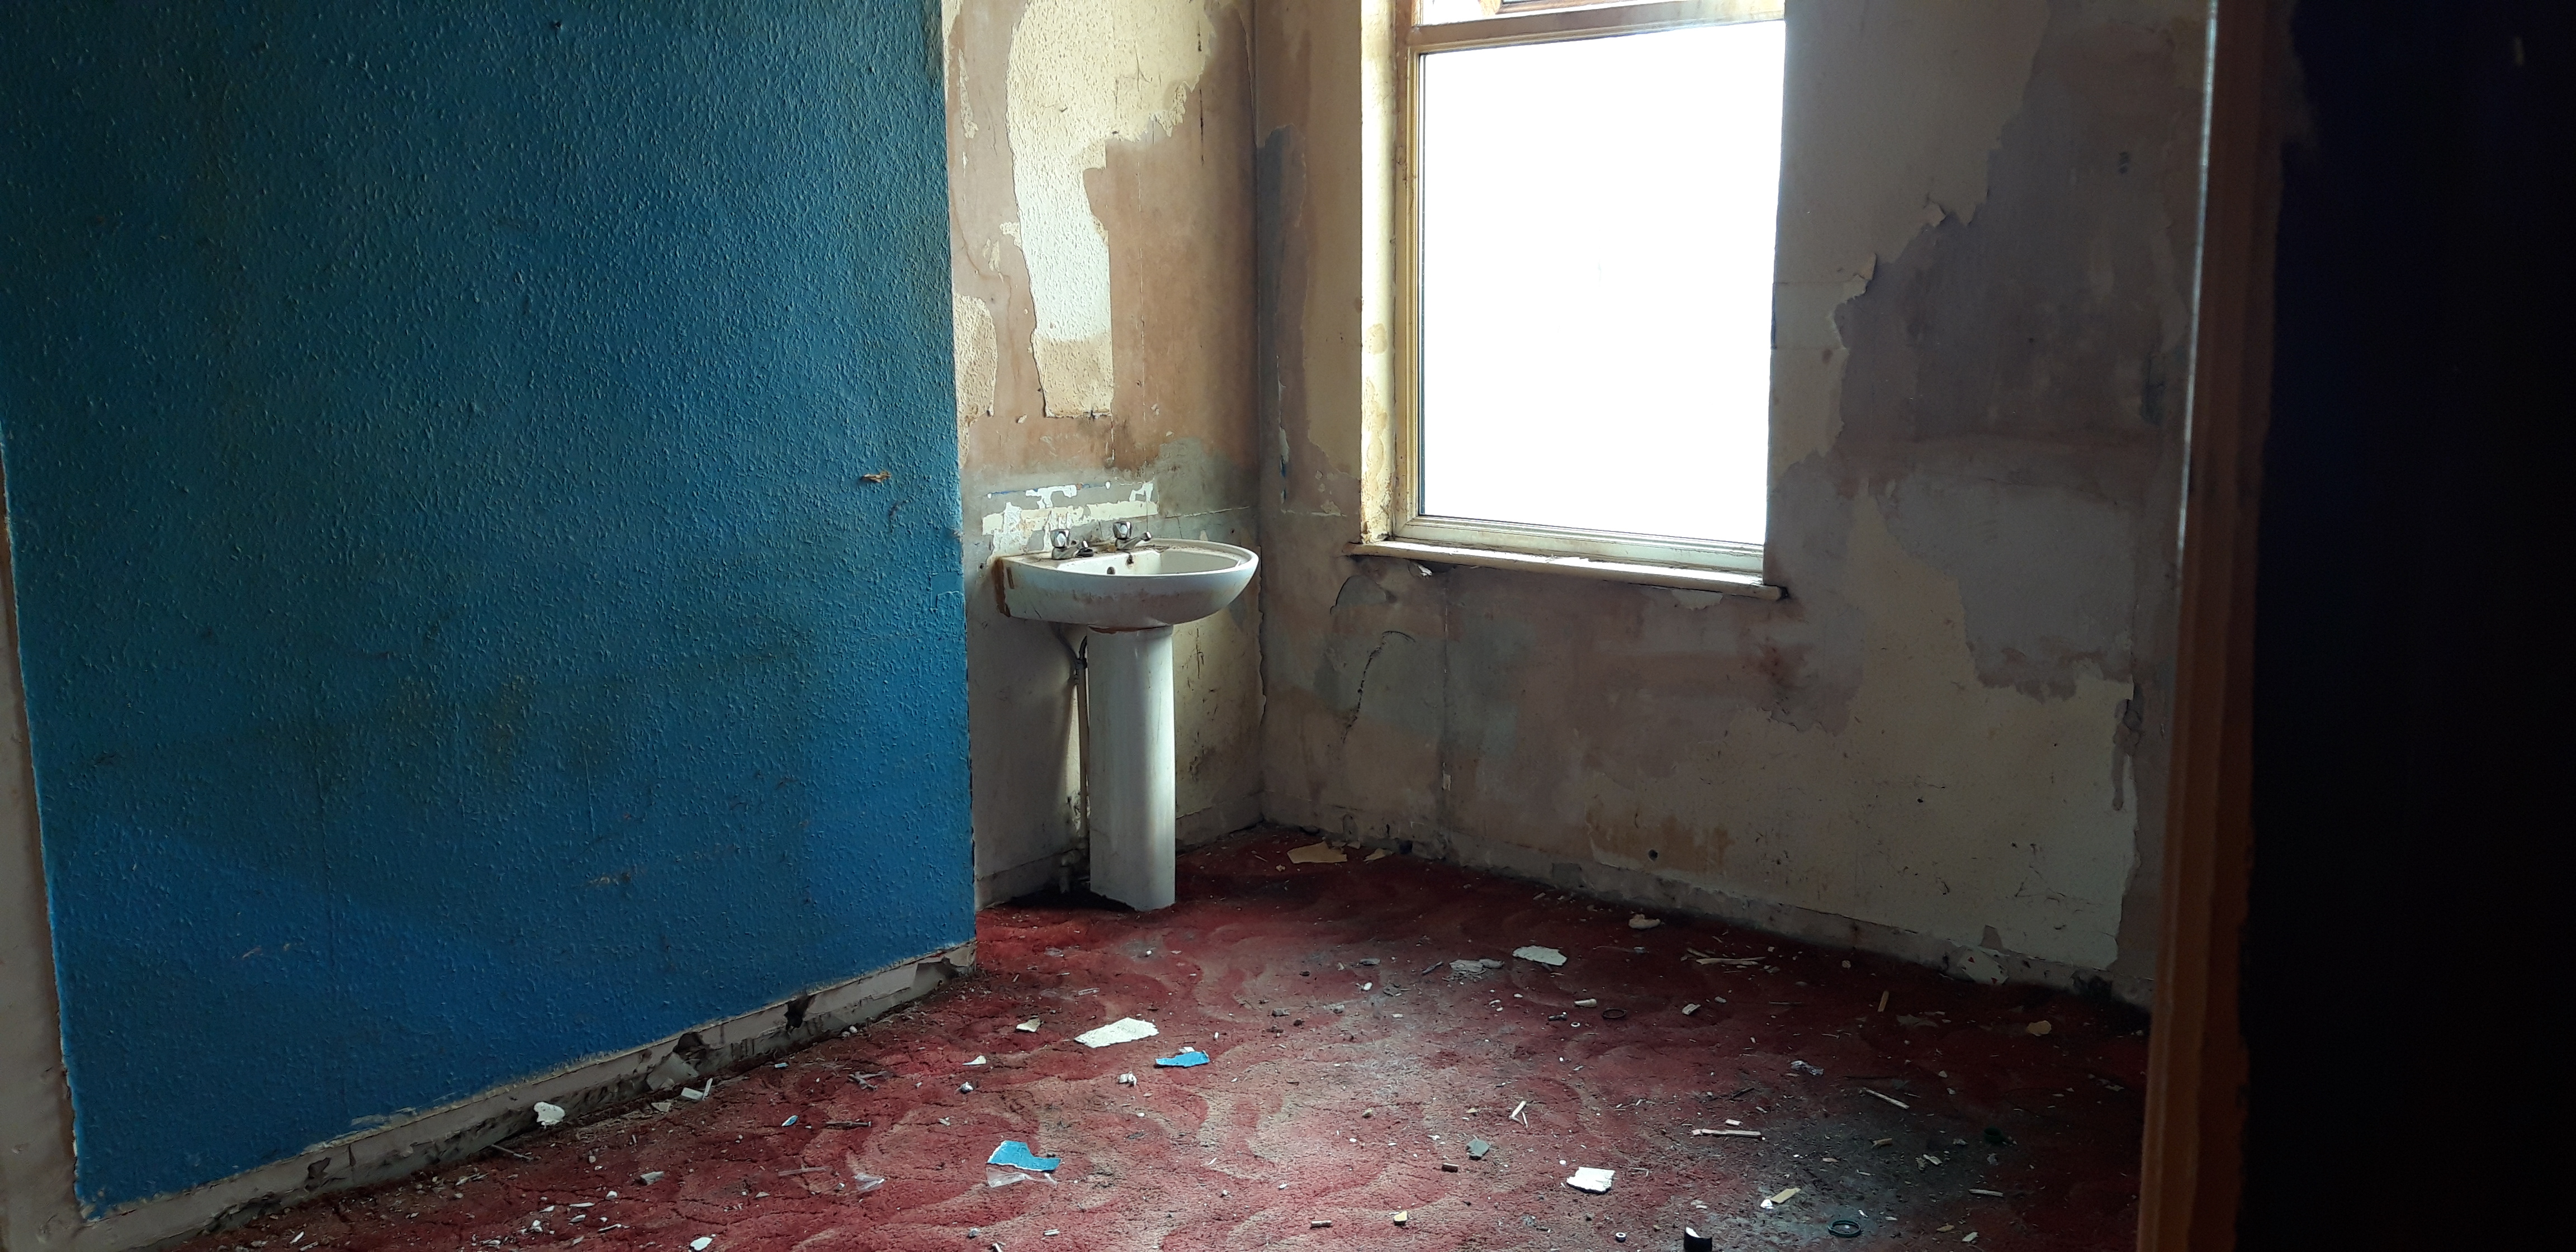
The property as we found it — dated, tired, and in significantly poorer condition than its licence status suggested.
The condition problem no licence can hide
The first issue was the condition of the building. It was old, tired, and clearly hadn't seen meaningful investment for some time. Technically, it had an HMO licence — which can sound reassuring at first glance, but that created a false sense of security. Many investors assume that if a property has an HMO licence, it must be compliant and ready to continue operating without major issues. In reality, that is not necessarily the case. Licensing standards change, property condition degrades, and what was acceptable several years ago may no longer meet current expectations.
The tenancy situation created another layer of complexity. Long-standing tenants often sound attractive because investors associate that with stable income and lower void risk — but this case was far from straightforward. The rents were significantly below market level, documentation was poor, and some of the occupiers had been there for many years. A few were older or vulnerable tenants, which naturally made any future plans more sensitive.
This is one of the major differences with large HMOs. With a standard buy-to-let, tenant management is relatively simple. With a large HMO — especially one with long-standing occupants in substandard accommodation — you are navigating a situation with human complexity attached to every decision.
The planning issue that nearly stopped everything
The biggest issue, however, was planning. The property had clearly been operating as an HMO for years, but when we started reviewing the paperwork properly, there was no clear evidence of formal planning permission for the use. That is a very different issue depending on the size and classification of the property, but for larger HMOs it can become critical. Without the right planning position, many lenders will simply walk away.
Because the property had historic use, our route was not to apply immediately for fresh planning consent, but to rely on proving continuous lawful use instead. That meant pursuing a Certificate of Lawfulness for Existing Use or Development — which required gathering evidence that the property had continuously operated in that form over the relevant period. It was time-consuming, document-heavy, and far more complicated than I had originally expected.
The lender that nearly killed the deal
At that stage, finance should have been the straightforward part. Instead, it nearly killed the deal.
At the time, I was not yet a qualified mortgage broker myself, so we used an external adviser. Unfortunately, this was one of those situations where the broker had some HMO knowledge, but not enough experience with more complicated specialist cases. The lender they recommended looked suitable on paper, but in practice it became clear they were the wrong fit.
The problem was not an immediate decline. A quick "no" is frustrating, but at least it allows you to move on quickly. The real danger is a lender that slowly drags the process out while repeatedly uncovering issues they should have identified much earlier. That is exactly what happened here. Weeks passed while underwriting came back with further questions, more document requests, and additional clarification requirements.
Meanwhile, the seller had made it clear they needed to complete before the end of the tax year or they would withdraw from the sale altogether. We were running out of time.
The bridging solution
To save the purchase, we switched to bridging finance and completed in around two weeks. That was not the original plan, and certainly not the cheapest route — but it got the deal done. In hindsight, it also created an opportunity. Once we owned the property, we could stop trying to preserve a tired inherited setup and instead reposition the asset properly.
The refurbishment
We carried out a full refurbishment — upgrading compliance, modernising the building throughout, and adding en-suite bathrooms to every room. This significantly improved both the rental profile and the long-term value. What had been a tired, underperforming asset became a well-specified professional lets product, properly positioned for its market.
After the full refurbishment
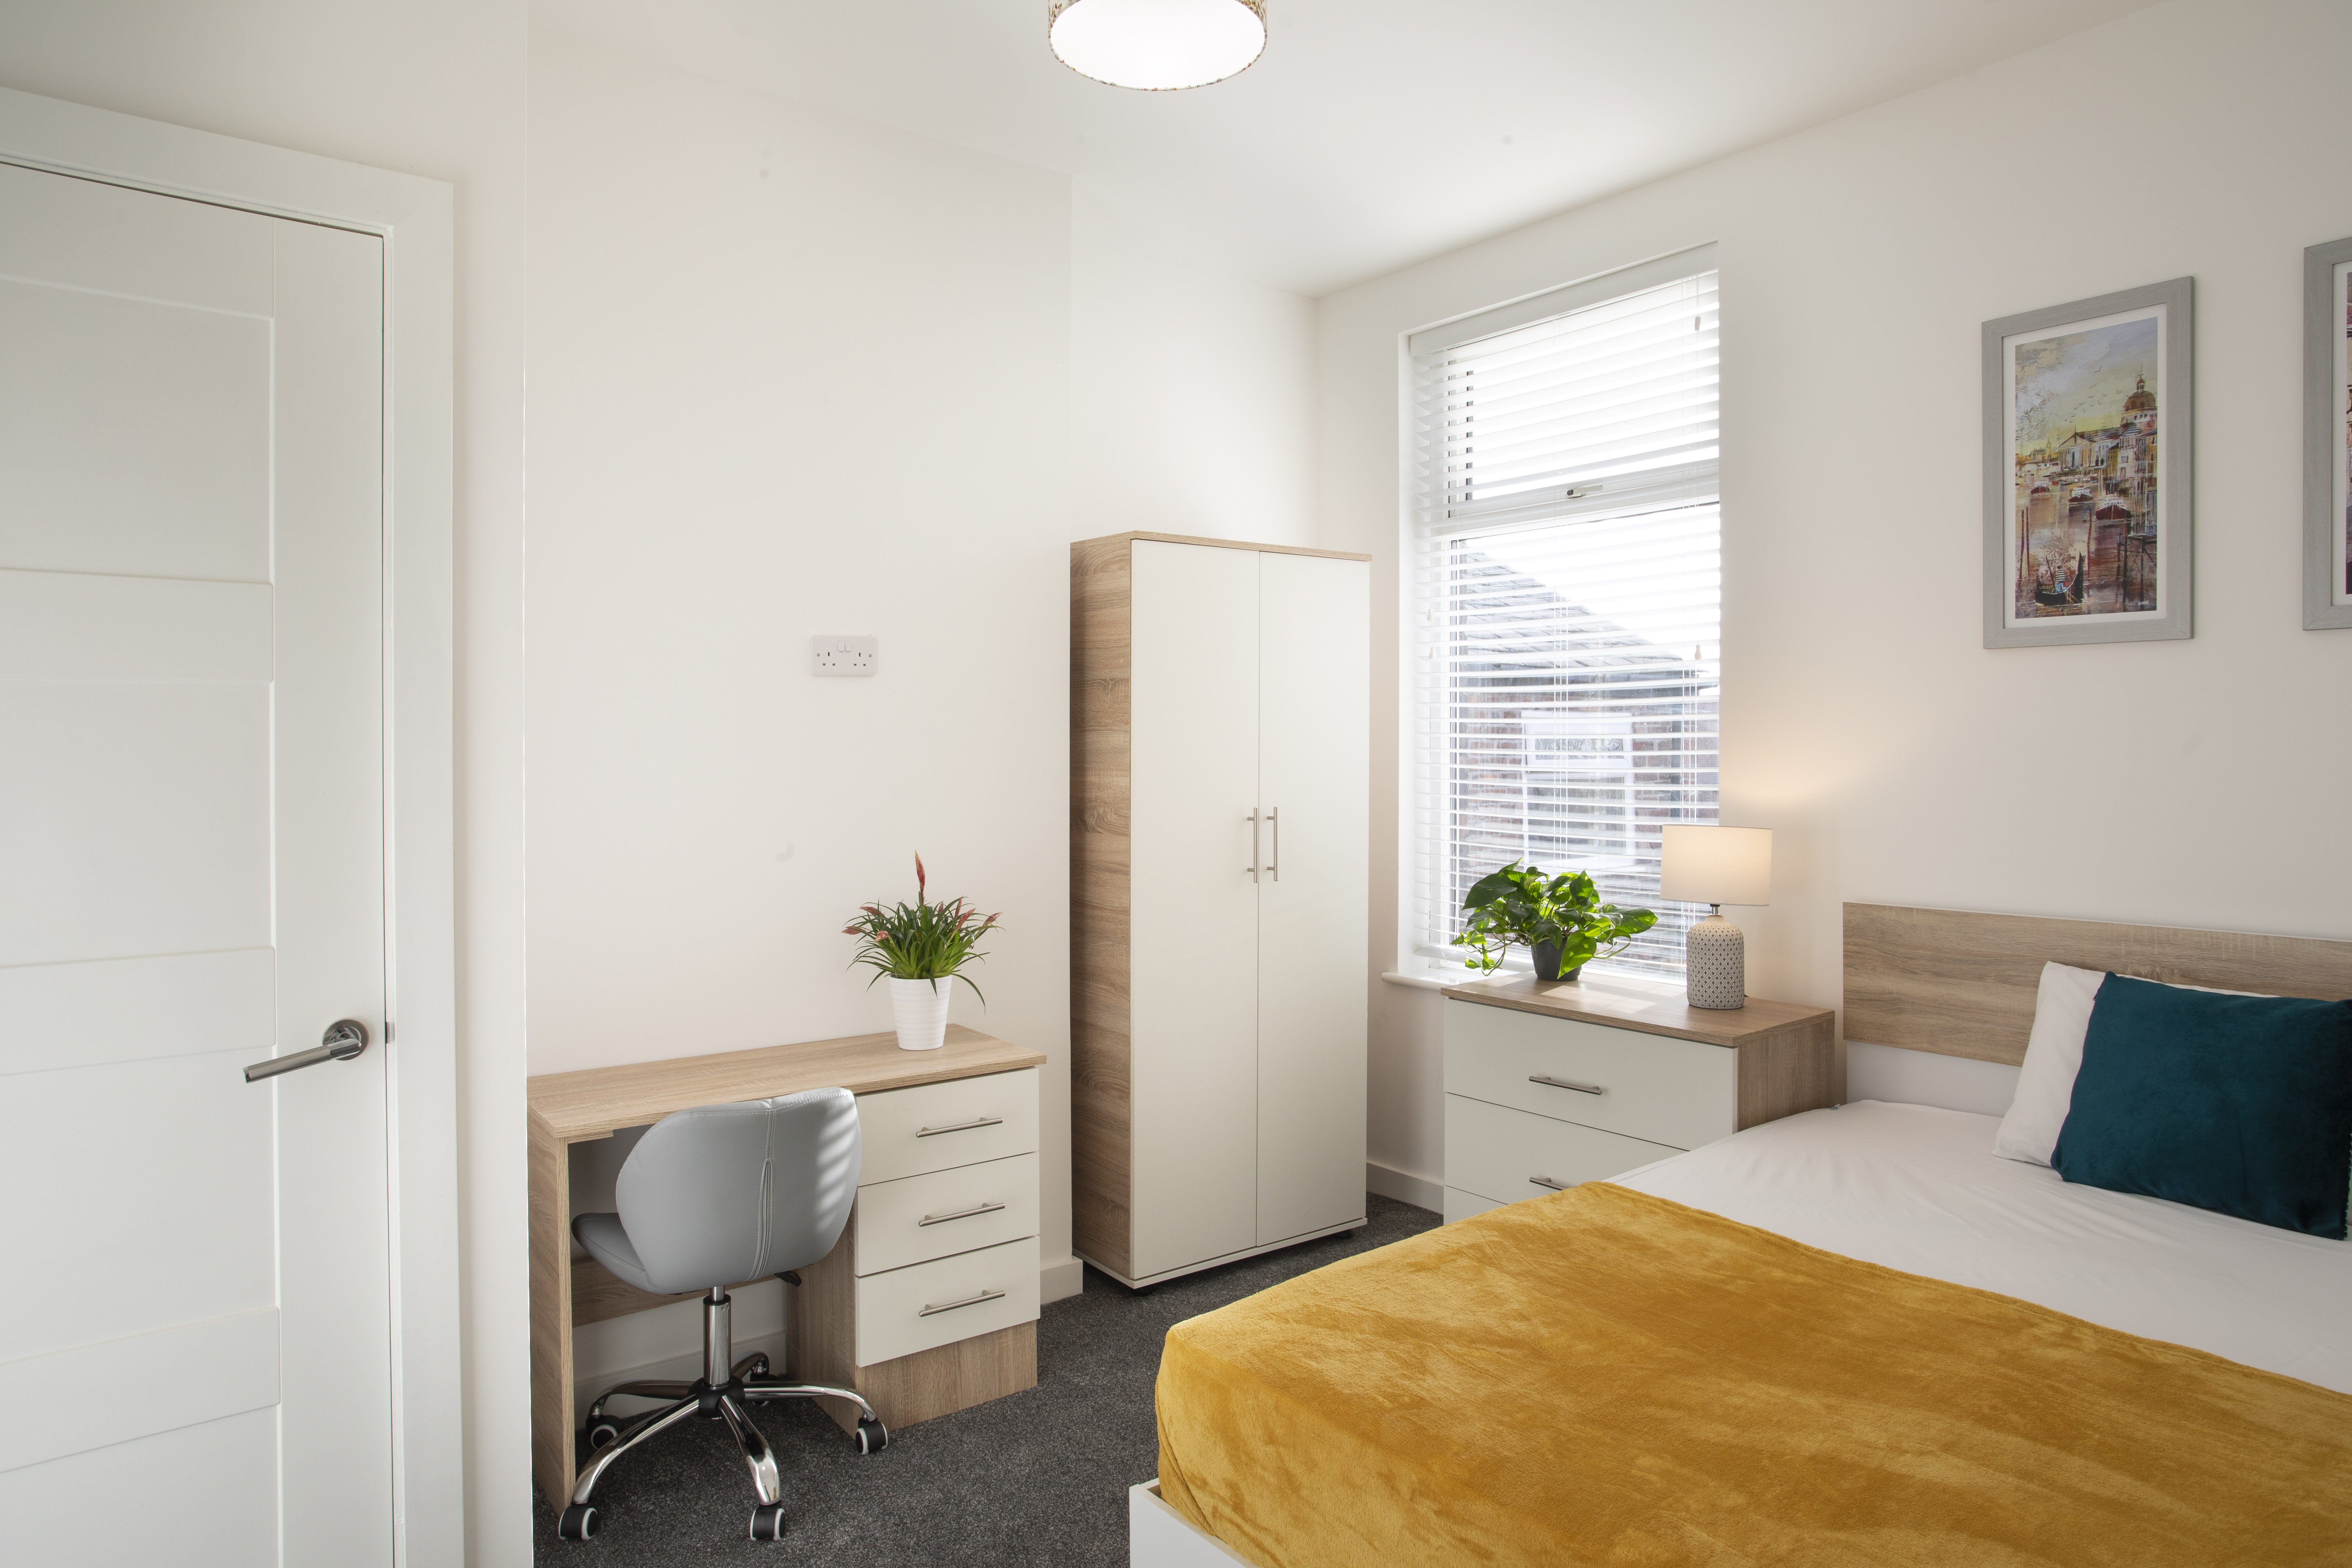
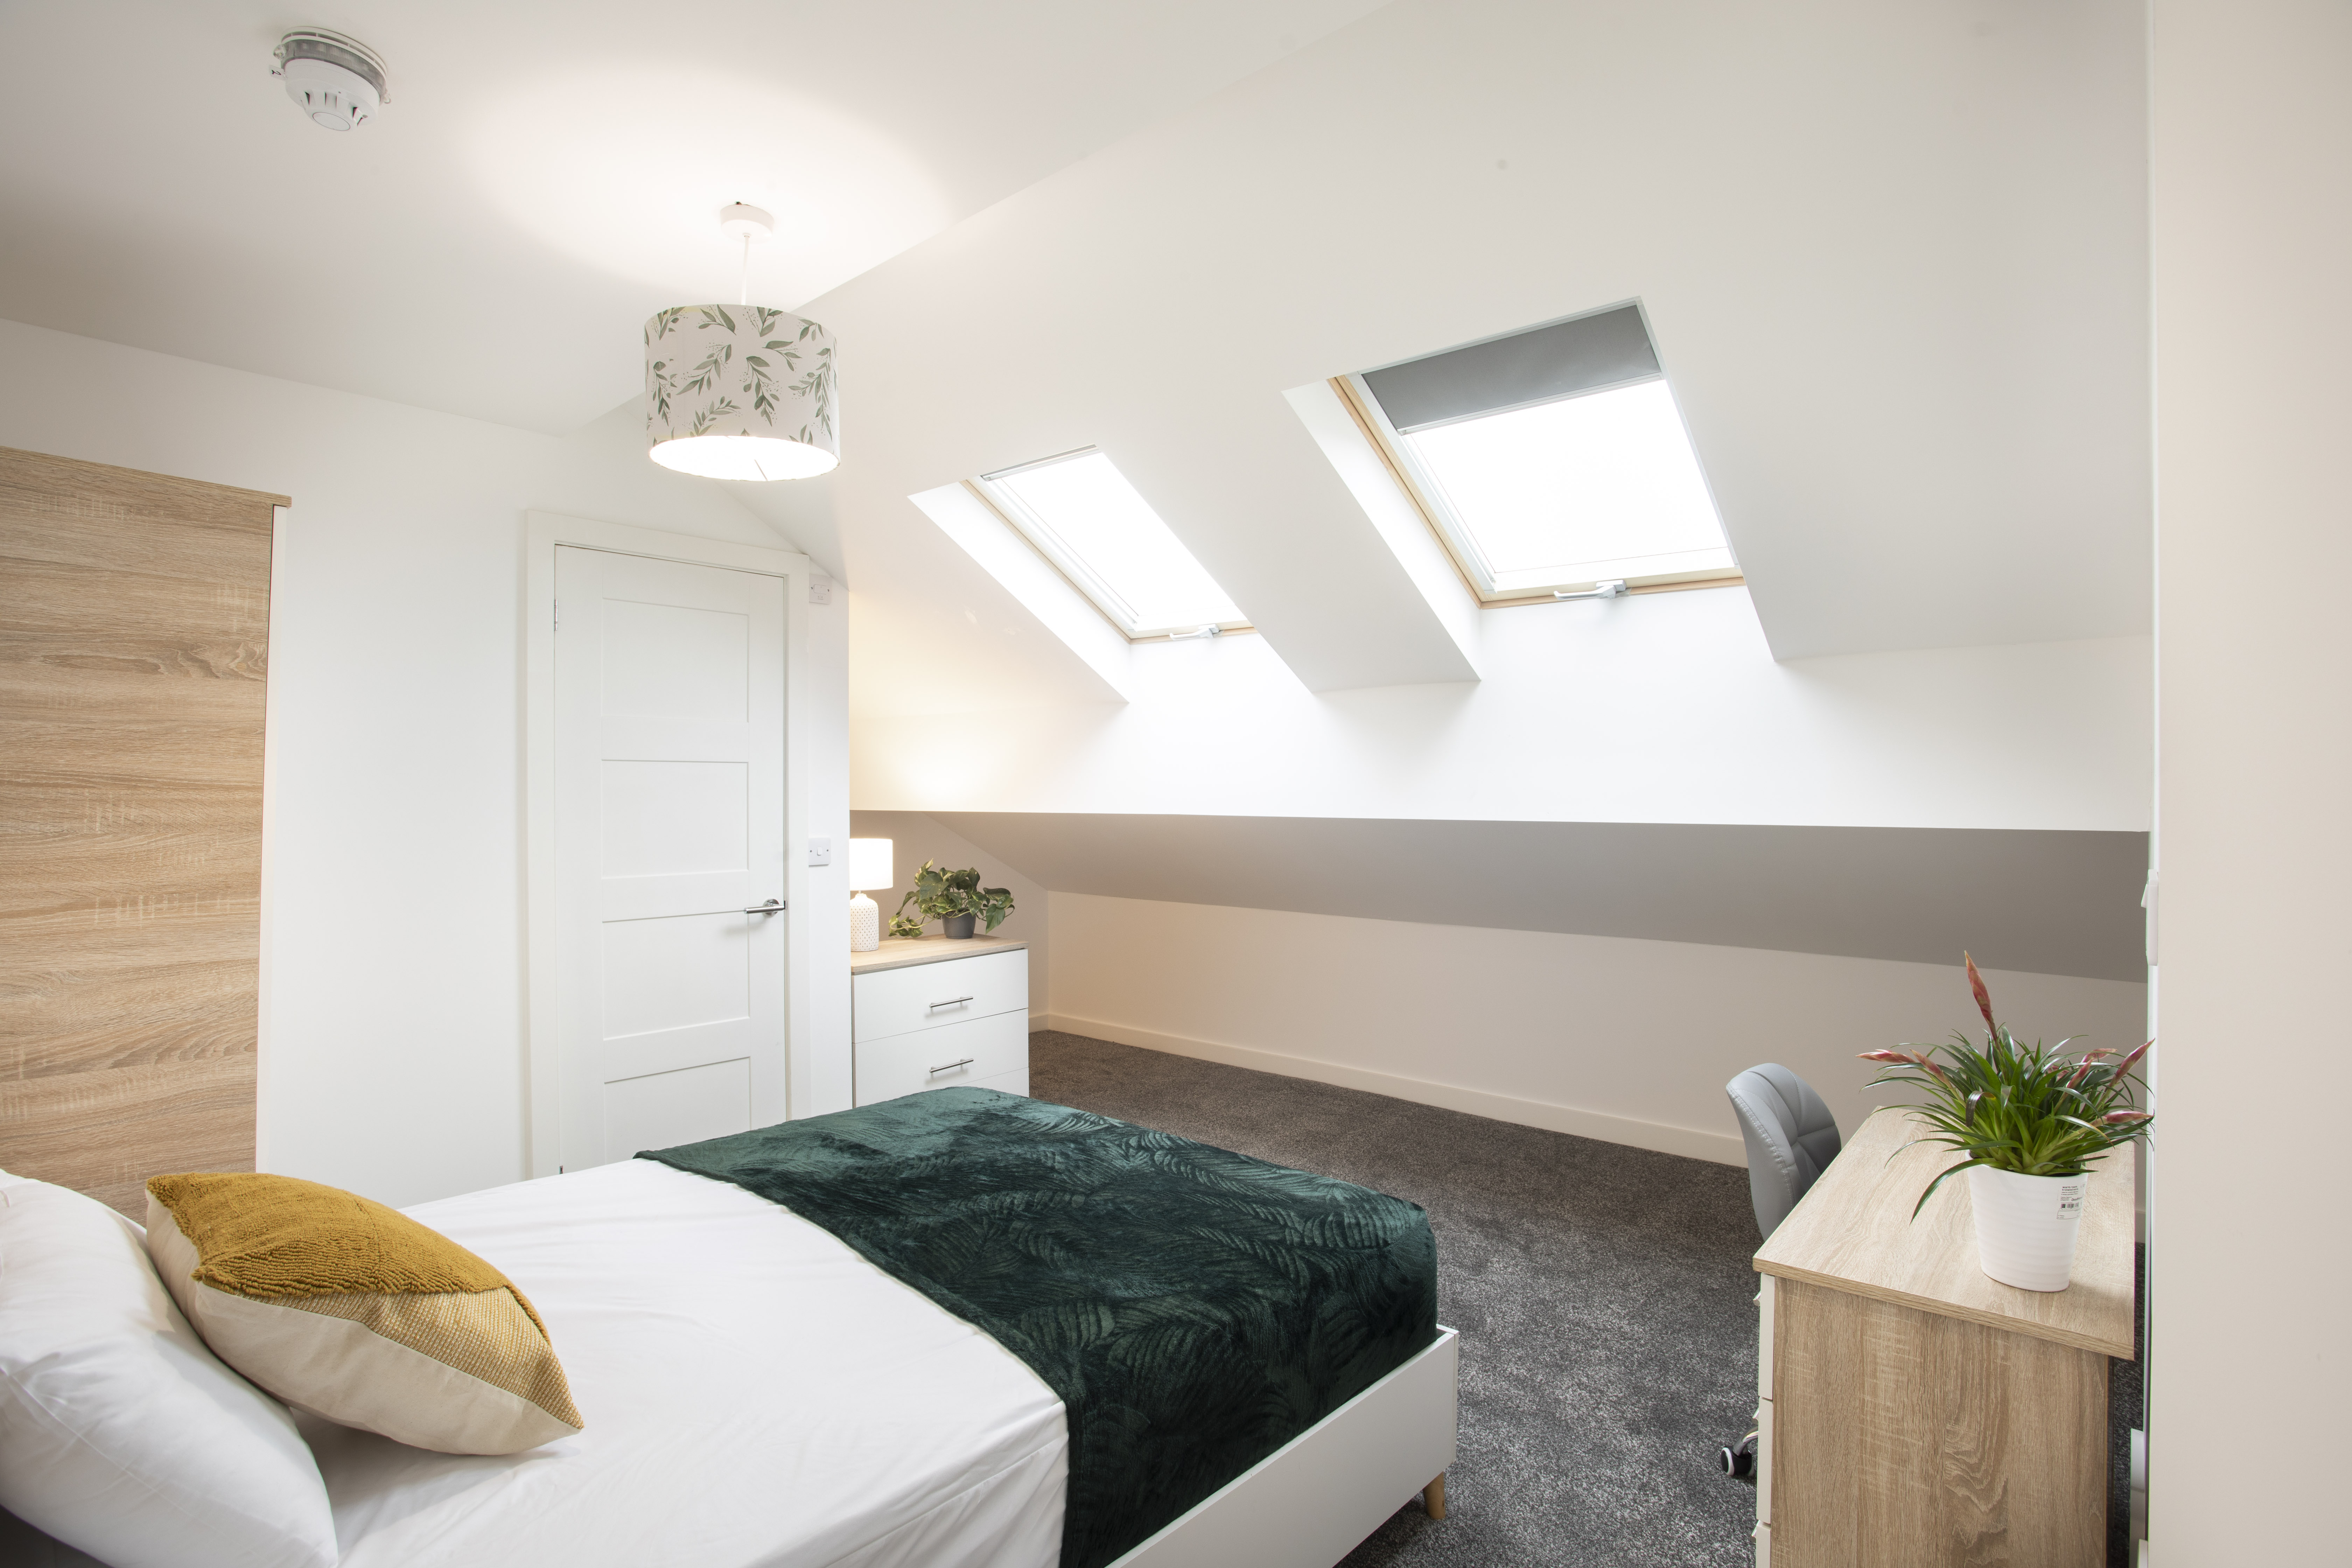
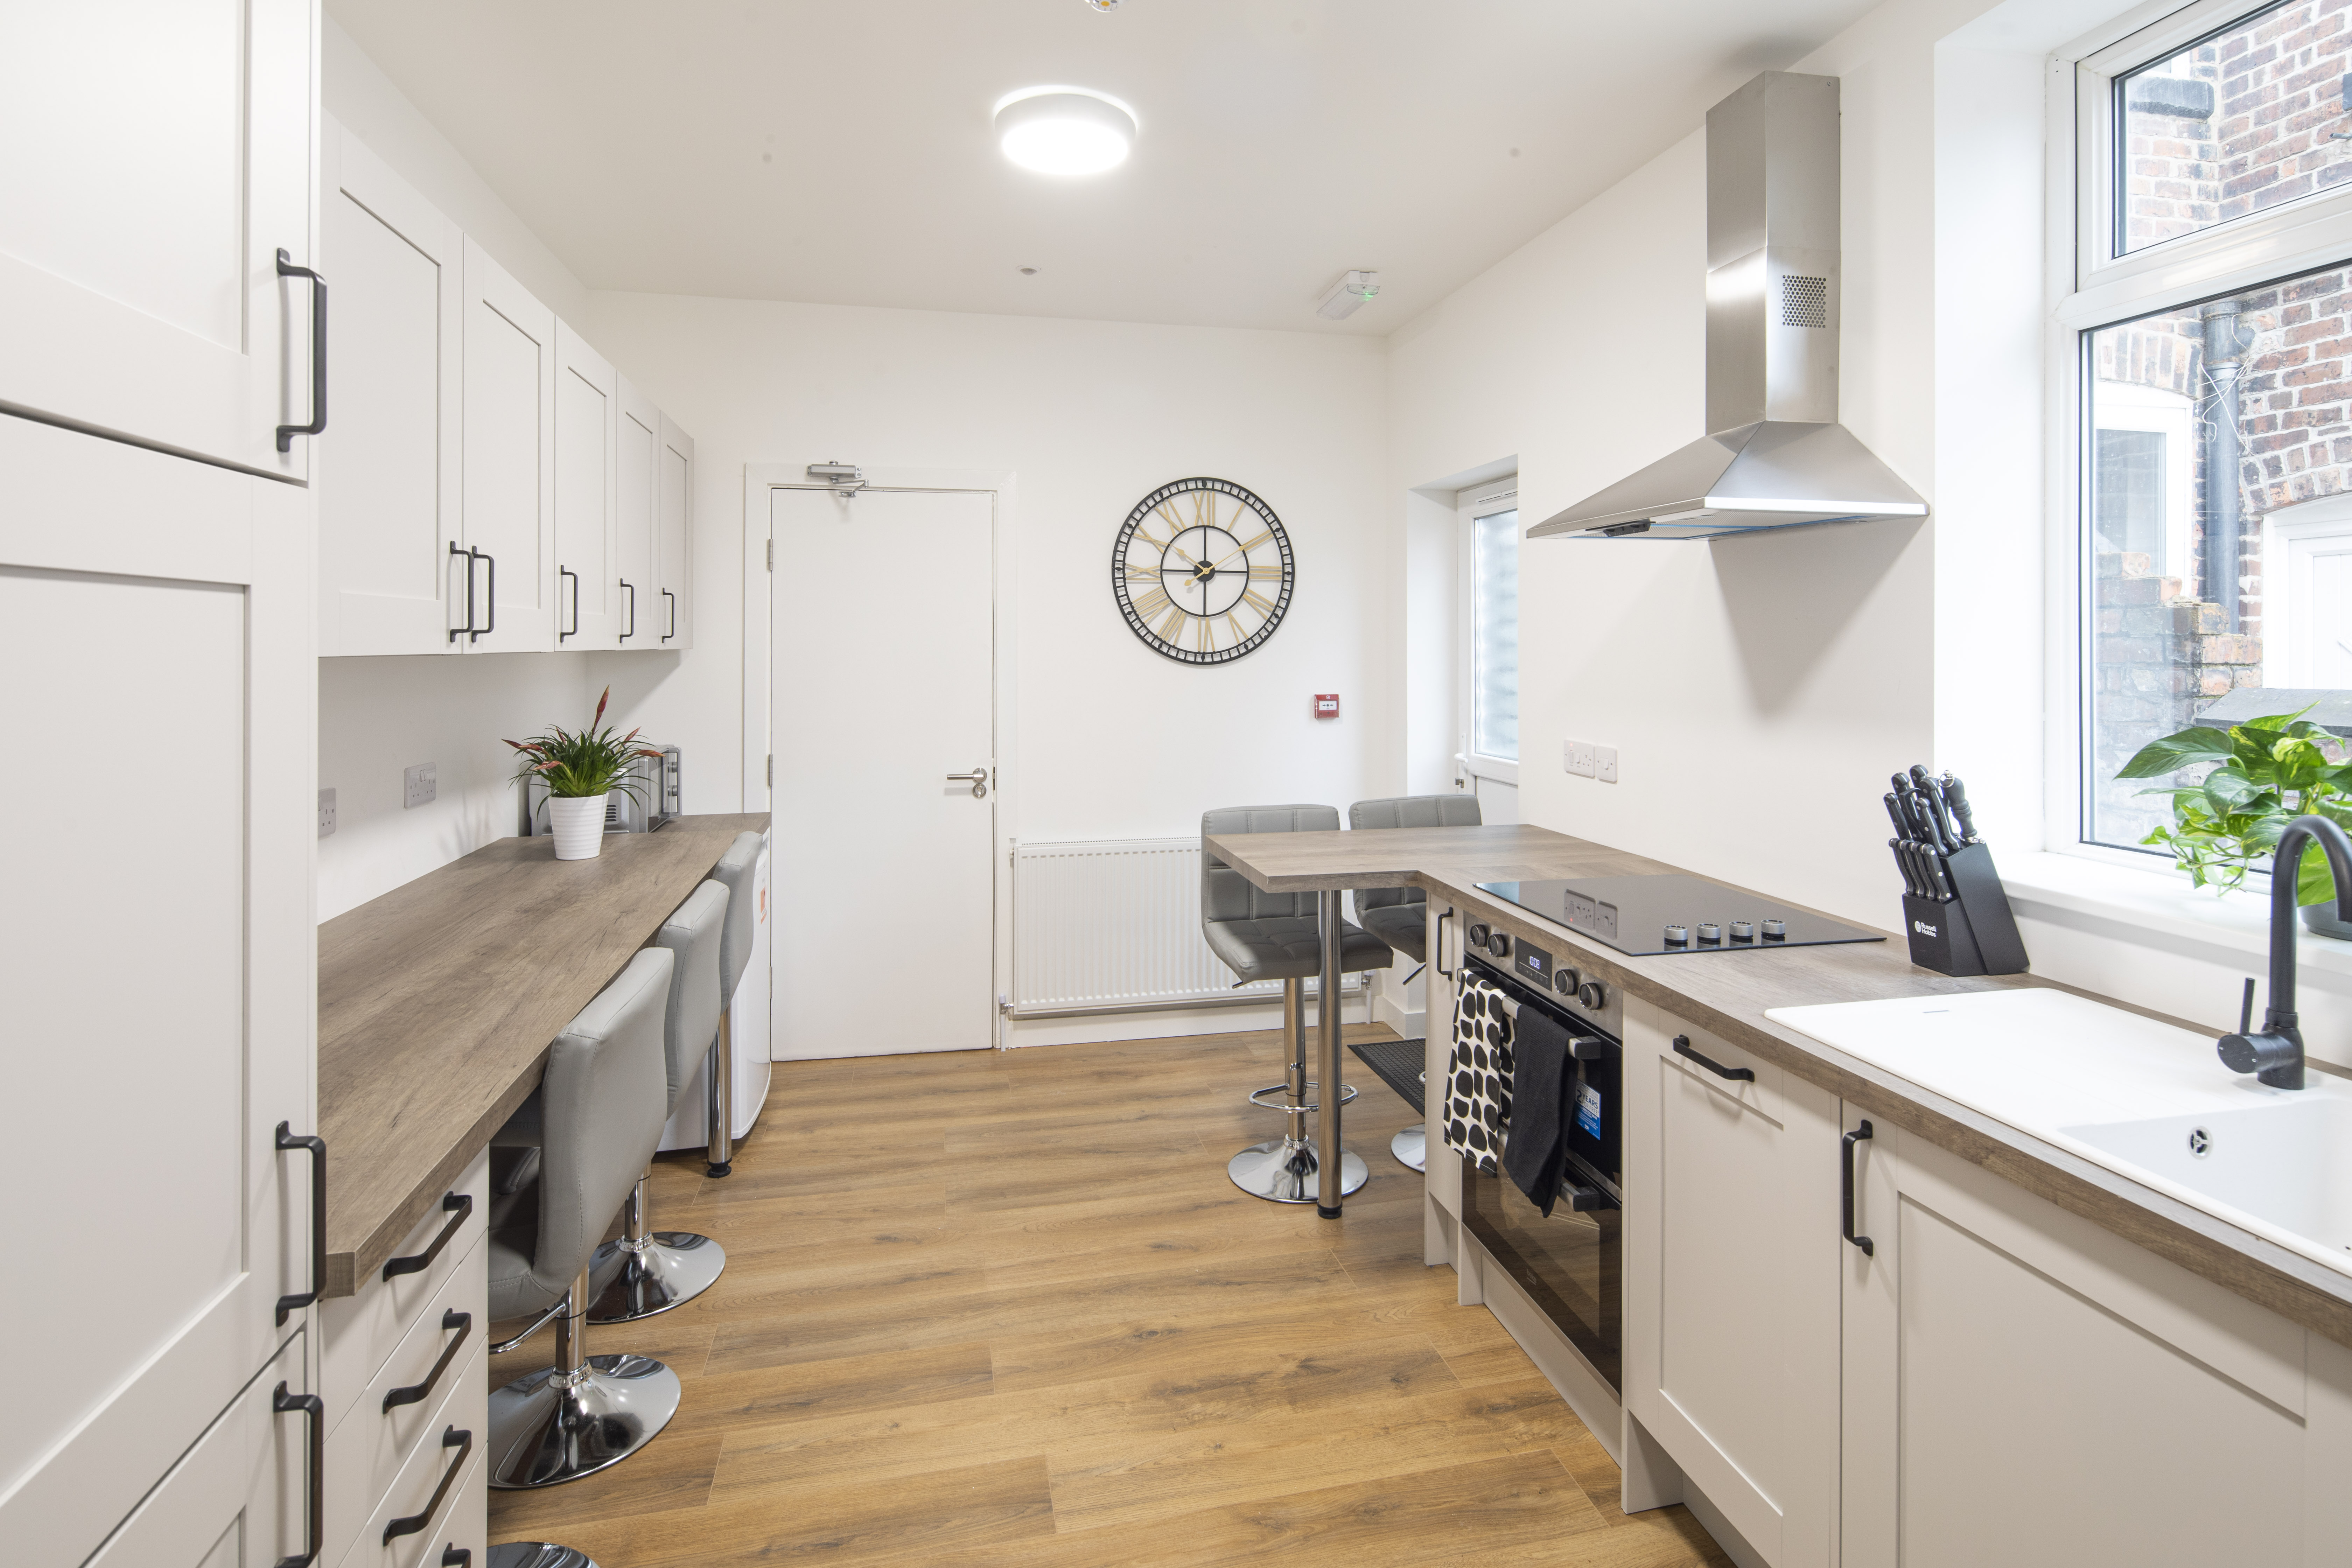
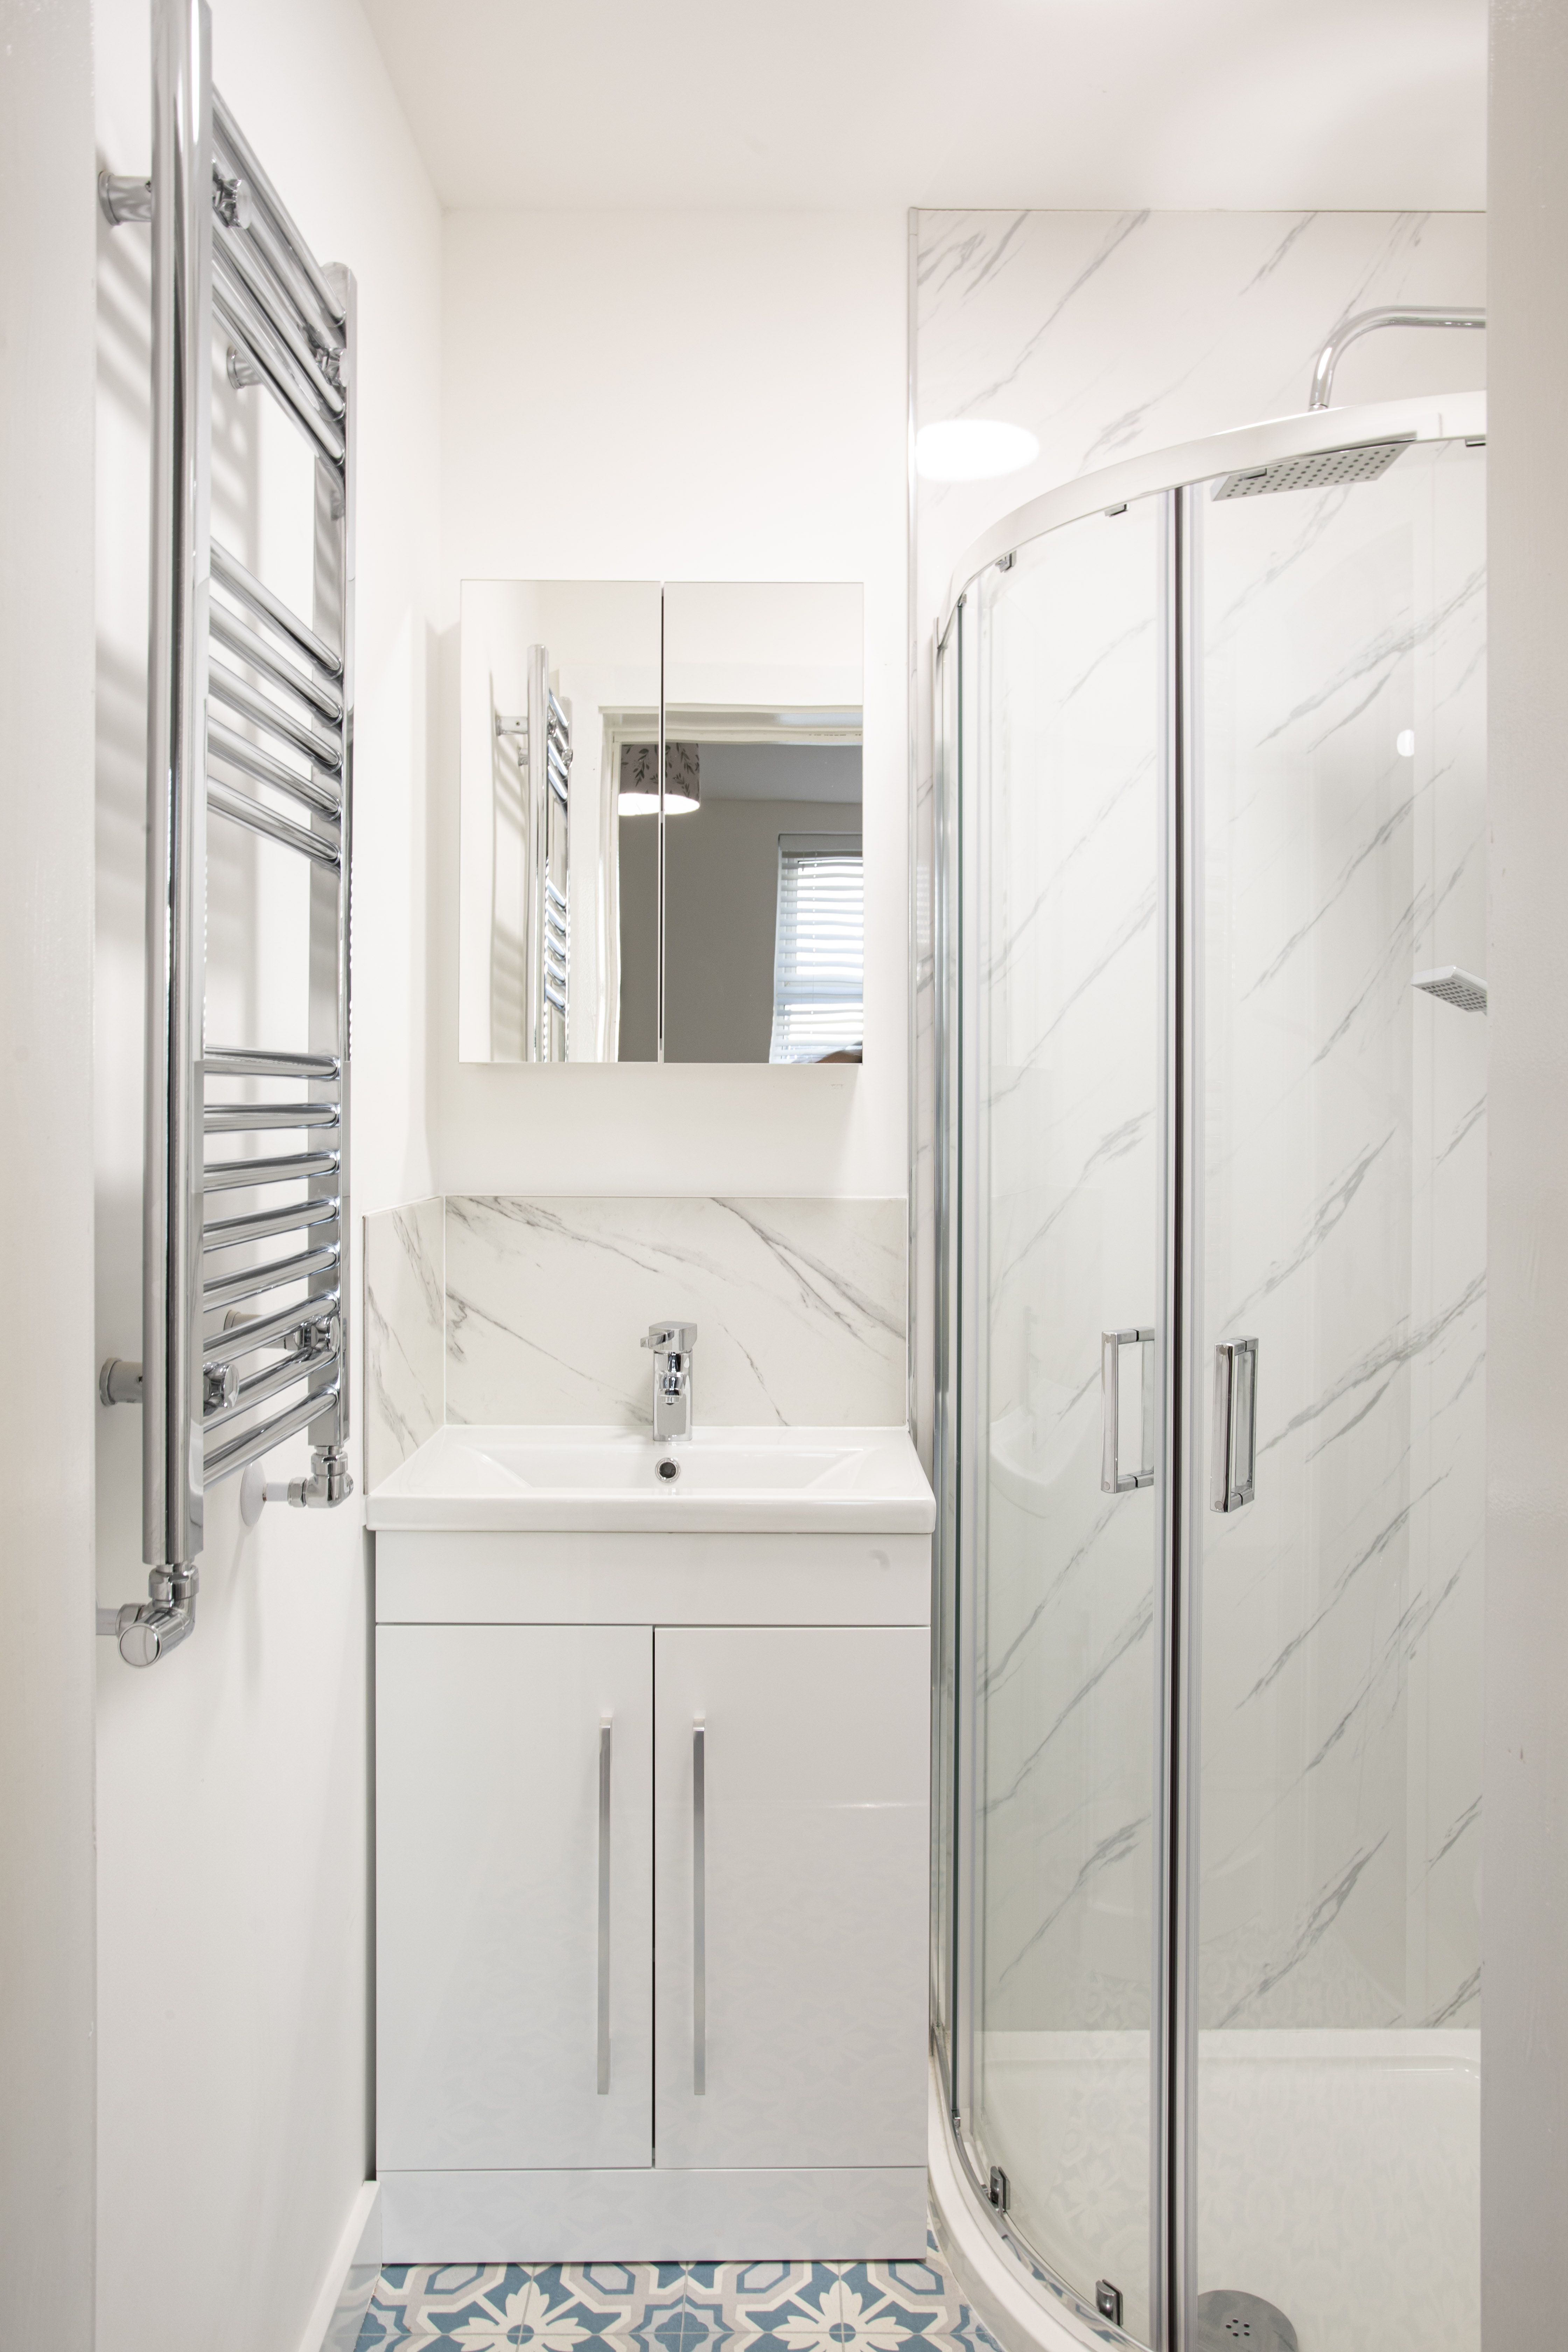
The same property after full refurbishment — en-suite bathrooms to every room, new communal kitchen, and modernised throughout.
The refinance — and its critical lesson
Once the works were complete, we refinanced onto a specialist HMO mortgage. That part worked — but there is a crucial lesson here for investors considering similar projects.
Never assume your refinance exit will be straightforward.
If your strategy involves using bridging finance to buy or refurbish a large HMO, your exit should be stress-tested before you complete. Some lenders will not refinance a property if you have owned it for less than six months. Others may lend, but at lower loan-to-value than expected. If your business plan relies on pulling most of your capital back out quickly, getting those assumptions wrong can leave you badly exposed.
That is why large HMO finance is about far more than simply finding a lender willing to say yes at the start.
The planning details most investors overlook
If you are converting a property into a large HMO, planning is about far more than internal layout and room sizes. Most investors immediately focus on fire doors, alarm systems, en-suites, and building regulations — all important — but some of the more difficult issues are external.
A property that looks perfect on paper can become much harder to finance if it sits next to a pub, takeaway, nightclub, or other commercial premises. Many lenders are cautious about residential investment properties located near certain commercial uses, particularly where noise or perceived tenant demand risk could become an issue.
Then there are practical considerations that seem minor until they become a genuine problem. Refuse storage sounds like a dull technical detail, but planning departments absolutely care about it for larger HMOs. Parking can become contentious depending on the area. And something as simple as double yellow lines outside the building can become a surprisingly expensive problem if you are planning major refurbishment works and suddenly realise skip access is not possible.
What large HMO finance actually involves
From a finance perspective, large HMOs sit firmly in specialist territory. If the property is already operational and mortgageable, there are lenders active in the space — but criteria are usually stricter than standard BTL lending. Experience matters more, portfolio exposure matters more, and lenders will often want far more detailed information about both the asset and the borrower's wider property business.
Valuation is another area where expectations often catch investors out. Standard buy-to-lets are usually valued on comparable sales. Larger HMOs are often assessed commercially — based on sustainable income and yield assumptions. That means your refinance valuation may not align with what nearby residential property values suggest, which is why structuring the exit correctly from the start matters so much.
Illustrative example — commercial investment valuation based on yield
To illustrate how a lender or valuer might assess a 7-room HMO, here is a simplified yield-based calculation. These are example figures only — actual valuations will depend on the specific property, location, and the assumptions individual valuers apply.
Income assumption
Yield-based valuation
Different valuers use different income and yield assumptions. A more conservative void allowance or a higher yield rate will reduce the valuation significantly — which is exactly why exit planning matters before you buy, not after. This example is illustrative only and does not constitute financial advice or a valuation.
Lenders active in this space
The number of lenders willing to look at large HMOs is smaller than for standard buy-to-let, and criteria changes regularly. At the time of writing, lenders that have been active in this area include:
This is not an exhaustive list, and lender appetite can shift quickly depending on portfolio exposure, product appetite, and wider market conditions. The right lender for your deal will depend on the property, your experience, and your wider portfolio — not just who is on any given list.
Documents lenders will want
Large HMO applications are document-heavy. Getting your pack together early avoids delays at the point when they can do the most damage. Expect lenders to ask for most or all of the following:
SA302s / tax overviews
Usually last 2–3 years
Company accounts
If borrowing through a limited company
Bank statements
Personal and/or business
Portfolio schedule
Full schedule of existing properties
AST / licence agreements
Current tenancy documentation
Rent schedule
Current and/or projected income
HMO licence
Mandatory licence where applicable
EPC
Energy Performance Certificate
Fire compliance docs
Alarm system, fire door certification
Asset & liability statement
Personal financial summary
Experience background
Evidence of prior HMO ownership/management
Business plan
Sometimes required, especially for complex cases
The bottom line
Large HMOs can be exceptional investments when approached properly. My own deal ultimately worked well, but it could just as easily have gone the other way. The biggest mistake I see investors make is assuming this is simply the next logical step after buy-to-let.
Sometimes it is. But only if you approach it as what it actually is: not just a larger rental property, but an operating investment business where planning, finance, compliance, and execution all matter far more than most people initially realise.